Snow Removal Insurance: The Gaps That Cost Contractors
Snow removal insurance is not one product — it is a stack of six coverage types. This guide covers what each pays for, the exclusions that cost contractors most, and the contract language that shifts a property owner's liability onto your balance sheet.
Snow removal insurance is not a single policy. Most contractors buy general liability, assume it covers slip-and-fall claims, and discover the gap during a lawsuit. The coverage that pays those claims is products-completed operations — it sits inside general liability when it is included at all. The claims that end snow businesses usually arrive through a contract clause.
What snow removal insurance costs
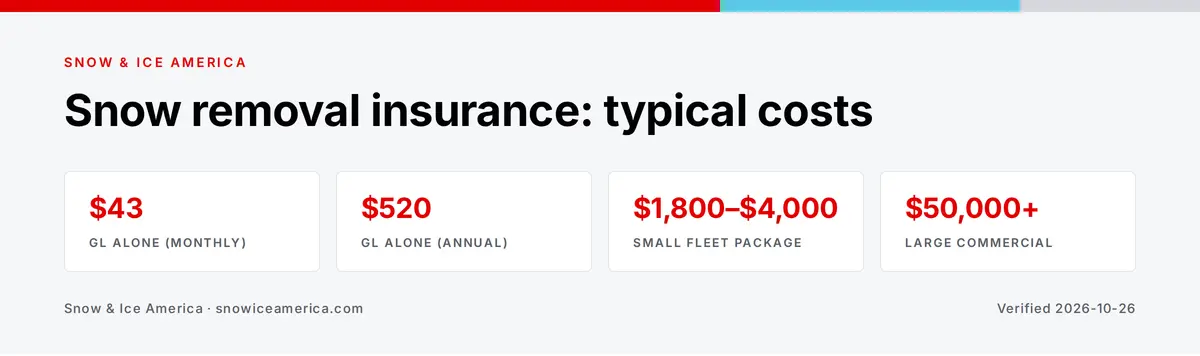
Snow removal insurance costs vary widely, and published averages are a starting point, not a quote. According to Insureon, snow removal contractors pay roughly $43 per month — about $520 a year — for general liability alone. A working package pairing general liability with commercial auto runs most small operations $1,800 to $4,000 a year, and larger multi-truck operations on commercial contracts can exceed $50,000.
The spread is large because premiums track risk, not fleet size. Six factors move the number most:
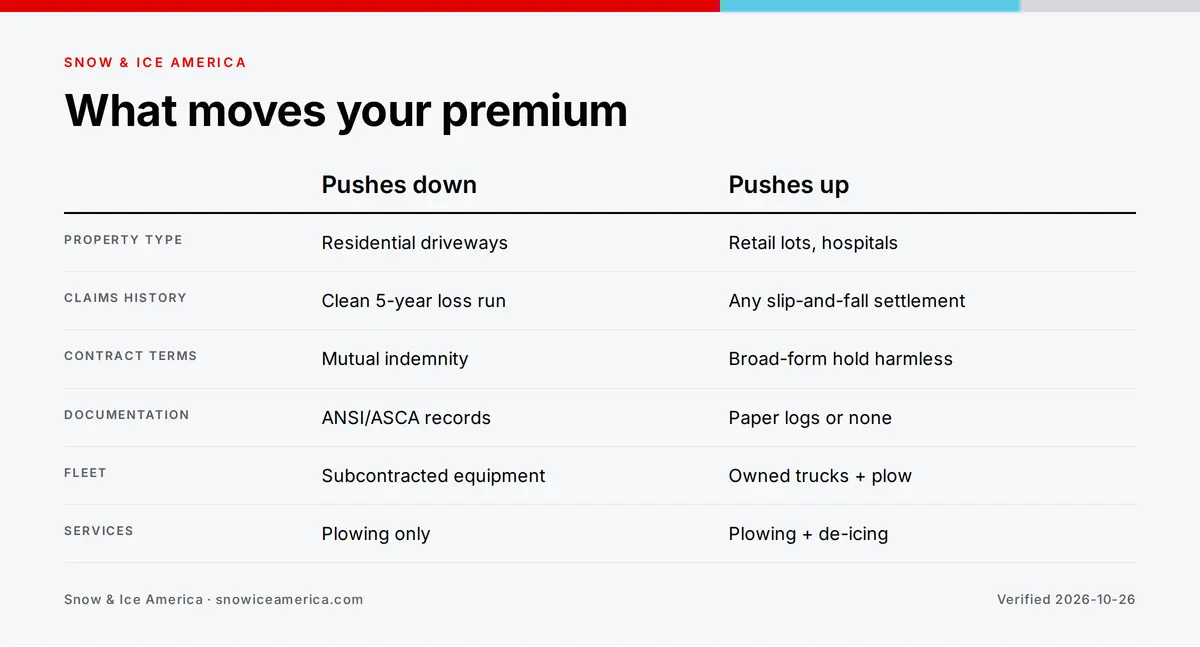
The biggest lever is property type: residential driveways carry the lowest risk; retail lots, hospitals and distribution centres sit at the high end. A clean five-year loss run pulls the rate down; any slip-and-fall settlement pushes it up. Contract terms also move the premium — mutual indemnity language limits exposure, while a broad-form hold harmless clause extends it. Documentation is within your control: carriers rate ANSI/ASCA-compliant service records lower than paper logs or none at all. Subcontracted equipment costs less to insure than owned trucks with plows attached. Plowing only is cheaper than a scope that includes de-icing.
De-icing deserves particular attention. Applying material is a judgement call about quantity, timing and surface temperature, and it exposes you to claims that plowing alone does not. Some carriers price or exclude de-icing separately.
The six policies, and which one pays a slip-and-fall
Six policies make up a complete snow removal insurance program; each covers a different event and pays a different kind of claim.
General liability — and the clause that actually matters
General liability insurance covers third-party bodily injury and property damage. For snow work the operative section is usually products-completed operations, not premises liability. A slip-and-fall almost never happens while your truck is on site; it happens hours after you left, on a surface you serviced. That claim arises from completed work.
Check that completed operations is included and that its aggregate is adequate. A policy covering you while plowing but limiting completed operations is close to useless in this trade.
Commercial auto — the plow-attached gap
Commercial auto covers the loss that general liability excludes: damage caused while the plow truck is in motion. This is the most common gap in snow removal insurance coverage. When your plow damages a bollard, a parked car or a kerb while the truck is in motion, that is an auto loss, not a general liability loss — and most general liability policies exclude losses arising from the operation of a vehicle. Contractors carrying solid general liability but thin commercial auto limits find that out at the worst possible time.
Confirm three things with your agent: that plows and spreaders are listed as attached equipment, that hired and non-owned auto is included if you use subcontractors’ trucks, and what your limit is per occurrence.
Workers’ compensation
Workers compensation insurance is mandatory in most states once you have employees. The rules on owner-operators and 1099 subcontractors vary by state. Misclassifying a crew member as a contractor does not remove your exposure; it usually just means the claim arrives uninsured.
Inland marine insurance — equipment away from your premises
General liability does not cover your own equipment. Inland marine insurance covers plows, spreaders, blowers and attachments in transit or at a job site. Given that a V-plow assembly runs several thousand dollars, it is inexpensive relative to what it protects.
Umbrella versus excess liability
Umbrella and excess liability policies are not interchangeable. Excess liability sits on top of one specific underlying policy and follows its terms exactly. Umbrella sits above several policies and can, depending on wording, cover some claims the underlying policies exclude. Commercial clients increasingly require $2m–$5m combined limits, which usually means one or the other.
Professional liability
Professional liability is relevant if you advise clients on service levels, write the snow plan, or make the call on when a site gets treated. It covers claims arising from that judgement rather than from the physical work.
The contract clause that moves the owner’s liability to you
Indemnity and hold-harmless language in service contracts does more financial damage than any coverage gap — and brokers rarely raise it.
Traditional snow removal contracts require the contractor to indemnify and hold harmless the property owner for incidents arising from the contractor’s work — frequently regardless of whether the owner was at fault. Sign a broad-form version and you have agreed to fund the defence of the party who failed to fix the drainage that created the ice. This risk exists across contract models — see flat-rate vs. pay-per-service pricing for how indemnity exposure interacts with which pricing structure you use.
Legislatures have started to intervene. Illinois was the first state to pass a Snow Removal Service Liability Limitation Act, making it against public policy — and therefore void — for a snow and ice removal contract to require indemnification or hold-harmless provisions covering a party’s own negligence (Marsh McLennan Agency). Colorado enacted comparable legislation restricting the enforceability of indemnity provisions in snow removal contracts (National Law Review). Similar bills have been enacted or introduced in Michigan, Wisconsin, Indiana, New York, New Jersey and Pennsylvania (Freeman Mathis & Gary).
Two practical consequences:
- A clause being unenforceable does not stop it being signed. You may still be pulled into litigation and spend real money establishing that the clause is void.
- Anti-indemnity law is state-specific and moving. The same contract template can be void in one state and fully enforceable in the next if you operate across state lines.
Have a lawyer in your operating state review your service agreement. This article is not legal advice, and the answer genuinely changes at the state line.
Documentation decides the claim
Insurers and defence counsel converge on one point: claims are lost on records, not on facts. More than 50% of snow and ice claims that are lost or settled are attributed to inadequate documentation — the contractor cannot prove what was done, on which surface, at what time (Green Industry Pros / ASCA).
The industry reference is ANSI/ASCA A1000-2014, an ANSI-accredited standard covering training, preseason site inspection reports, in-event documentation, post-event procedures and weather service records. Plaintiff and defence attorneys both reference ANSI standards once a claim is filed; a contractor who demonstrably followed one argues from a materially stronger position.
At minimum, per site per event, record:
- Time on site and time off site
- Surface temperature and precipitation at time of service
- Material applied — product and quantity
- Areas serviced, and any areas deliberately not serviced, with the reason
- Photographs on arrival and on departure
- The independent weather record for that event
Retain records for at least your state’s statute of limitations on personal injury — commonly two to three years, but confirm locally.
Certificates of insurance and subcontractors
Subcontractor insurance lapses become your problem the moment you signed them onto your routes. Manage it deliberately:
- Collect a certificate of insurance from every subcontractor before they turn a wheel, and verify it directly with the issuing agent rather than accepting a forwarded PDF.
- Require that you are named as additional insured on their general liability policy.
- Confirm their coverage runs for the whole season. Mid-season lapses are common, and they become your problem.
- Match limits. A subcontractor carrying $500k behind your $2m commitment is an uninsured gap wearing a certificate.
Aggregate limits — the number that runs out
Every general liability policy carries a per-occurrence limit and a general aggregate, the total it will pay across the policy period. A $1m/$2m policy pays at most $1m on any one claim and $2m in the year.
Snow is unusual because claims cluster. A single ice event across a portfolio of sites can generate several claims in one week. Two moderate settlements plus defence costs can consume an aggregate before February, leaving you effectively bare for the rest of the season while still under contract. Ask your agent about aggregate reinstatement options before the season, not during it.
Richard Delonge
EditorialThe Snow & Ice America editorial team tests and reviews plows, spreaders, and fleet tools with working contractors across North America. Independent. Never sponsored.
Price your next snow job in 60 seconds.
Estimate per-push, per-inch and seasonal pricing for any lot.